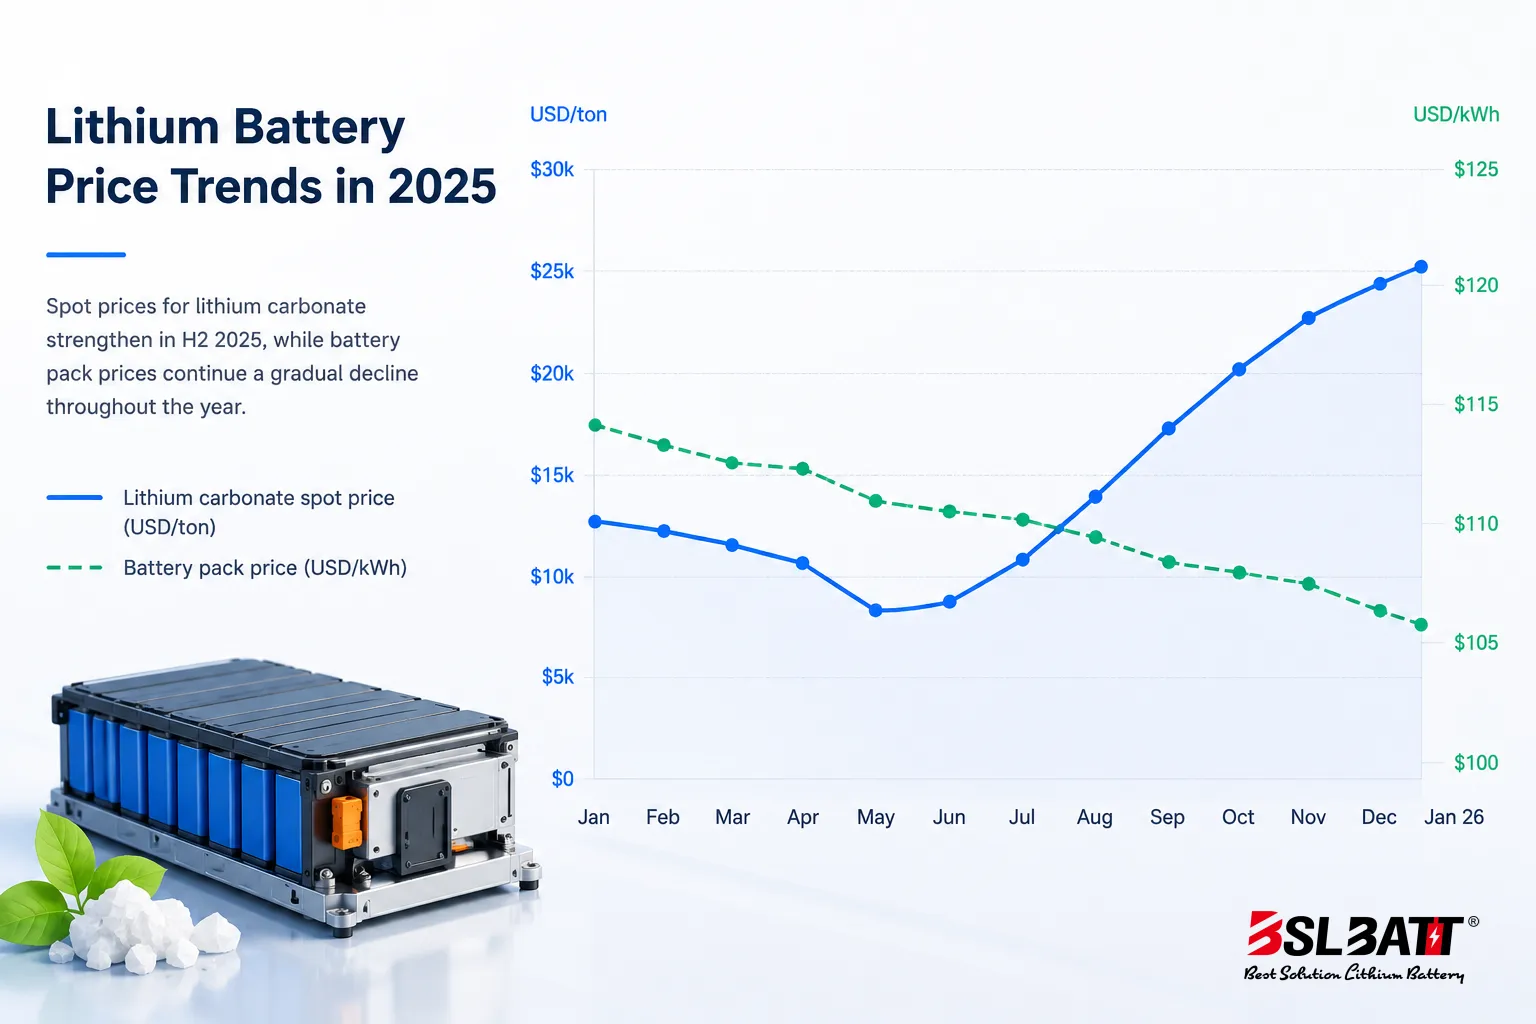
Lithium battery prices in 2025 split across two supply chain layers. Finished pack prices fell to a record $108/kWh by year-end (BloombergNEF), as manufacturers absorbed rising input costs through LFP adoption and long-term contracts. Battery-grade lithium carbonate spot prices rebounded over 90% from a June trough of $8,100/ton, driven by energy storage demand growth, low inventory in China, and the CATL Jianxiawo mine suspension. Finished battery prices remain near historic lows, but sustained raw material pressure may push pack pricing higher in 2026.
Lithium battery prices have gone through one of their most complex years in recent history. For most buyers, 2025 looked like a continuation of the multi-year cost-down trend. Pack prices hit record lows and procurement conditions were favorable across EV, forklift, solar storage, and commercial energy storage applications. Behind that headline, however, the raw material market was moving in the opposite direction. Lithium carbonate prices bottomed out in mid-2025 and then more than doubled by early 2026 as energy storage demand accelerated beyond forecasts, Chinese inventory drew down rapidly, and a key mine suspension removed roughly 6% of global lithium supply. Understanding both layers, finished battery economics and upstream raw material dynamics, is what buyers need to make informed procurement decisions for the period ahead.
Lithium Battery Price Overview
Lithium battery prices vary significantly by application, chemistry, and region. The table below provides a current reference across common use cases.
| Application / Metric | Cost Range / Value |
|---|---|
| Global average lithium battery pack price (2025) | $108/kWh (record low, BloombergNEF) |
| China average pack price (2025) | $84/kWh |
| Electric vehicle battery pack | $4,760 to $19,200 per pack |
| 2 to 2.5 Ah (industrial tools) | Around $110 |
| 4 Ah | Around $141 |
| 8 to 9 Ah | Around $220 |
| 10 to 12 Ah | Around $335 |
| Battery lifespan (charge cycles) | 1,000 to 3,000 cycles |
| Typical lifespan in EVs and storage | Up to 10 years |
Prices in 2025 continued a multi-year downward trend for finished battery packs. This has made lithium batteries more accessible across transportation, renewable energy, and industrial logistics.
2025 Average Price per kWh
The global average lithium-ion battery pack price reached a record low of $108/kWh in 2025, an 8% year-on-year decline from $115/kWh in 2024. China maintained the lowest prices at $84/kWh, while the United States and Europe remain 31% and 48% higher respectively, reflecting differences in manufacturing scale, labor costs, and supply chain maturity.
This decline occurred despite rising raw material costs. Battery metal prices increased through 2025, including lithium and cobalt, but manufacturers absorbed these pressures through greater LFP adoption, long-term supply contracts, and continued manufacturing efficiency gains. Stationary storage pack prices saw the sharpest improvement of any segment, falling to $70/kWh in 2025, a 45% single-year decline and the lowest-priced segment in the market for the first time.
| Year | Global Avg Pack Price (USD/kWh) | China Pack Price | BESS Pack Price |
|---|---|---|---|
| 2010 | Approx. $1,000+ | N/A | N/A |
| 2017 | $140 | N/A | N/A |
| 2023 | $139 | ~$105 | N/A |
| 2024 | $115 | ~$99 | $125 |
| 2025 | $108 (record low) | $84 | $70 (record low) |
| 2026 forecast | ~$105 | Continued decline | Continued decline |
Price by Application
Lithium battery prices vary by application, capacity, and supplier. EV battery packs in 2025 typically range from $4,760 to $19,200 per pack depending on size and manufacturer. A 48V 200Ah lithium battery at approximately 9.6 kWh is priced between $2,227 and $11,000, reflecting variation across specifications and suppliers.
For solar and stationary energy storage systems, battery packs cost between $6,000 and $12,000 for a 10 kWh residential system. In the golf cart sector, lithium battery prices range from $1,500 to $4,500 per set for 48V systems with capacities between 100Ah and 300Ah.
| Application | Specifications | Cost Range |
|---|---|---|
| EV battery pack | 40 to 200 kWh | $4,760 to $19,200 |
| 48V 200Ah lithium battery | 9.6 kWh | $2,227 to $11,000 per unit |
| Lithium golf cart battery | 48V 100 to 300Ah | $1,500 to $4,500 per set |
| Lithium-ion solar battery | 10 kWh | $6,000 to $12,000 per system |
Yearly Price Trend
The lithium battery pack price has dropped consistently over the past several years. In 2023, the global average stood at $139/kWh. In 2024, it fell to $115/kWh, a 20% year-over-year decline. In 2025, it reached $108/kWh as a record low.
Battery material prices also declined sharply leading into this period. Lithium carbonate fell from approximately $70,000 per metric ton in 2022 to below $15,000 in 2024, with the spot price bottoming at around $8,100/ton in June 2025. However, raw material prices reversed sharply in the second half of 2025. By early 2026, lithium carbonate had climbed to approximately $24,000 to $26,000/ton. The IEA confirmed that lithium prices at the start of 2026 were more than twice the level seen in the same period of 2025.
This divergence between rising raw material prices and still-falling finished pack prices is the defining market dynamic heading into 2026.
Price Drivers
Three structural forces shape lithium battery prices: raw material costs, manufacturing efficiency, and government policy. Each operates on a different timescale and affects pack prices in different ways.
Raw Materials
Raw materials account for over 70% of the cost of a lithium-ion battery cell. Lithium, cobalt, and nickel are the most significant inputs. Their prices shift with supply and demand, and sharp swings in either direction flow through to finished battery costs.
From 2022 to mid-2025, lithium prices fell nearly 90% as global mining output expanded and EV demand grew more slowly than expected. Cobalt prices dropped by more than half in the same period. BloombergNEF data shows that in 2023, EV battery packs averaged $128/kWh and cells alone averaged $89/kWh. Cells make up approximately 78% of total pack cost. China leads with the lowest battery prices, while the United States and Europe pay more due to higher production costs and less mature local markets.
In 2025, this trend reversed for raw materials even as pack prices continued falling. The suspension of CATL’s Jianxiawo mine in Jiangxi province from August 2025 removed approximately 6% of global lithium output from the market and triggered a sharp increase in spot lithium carbonate prices. Fastmarkets and Benchmark Mineral Intelligence noted that this supply disruption, combined with very low inventory levels and accelerating energy storage demand, shifted the market balance significantly.
Manufacturers absorbed higher raw material costs in 2025 through greater LFP adoption and long-term supply contracts rather than passing costs to buyers. Whether this absorption continues into 2026 depends on how long raw material prices remain elevated.
| Raw Material | 2022 Peak | Mid-2025 Trough | Early 2026 Level |
|---|---|---|---|
| Lithium carbonate (battery grade) | ~$70,000/ton | ~$8,100/ton | ~$24,000 to $26,000/ton |
| Cobalt | Multi-year high | Approx. 50% below 2022 | Rising on DRC export quota tightening |
| Nickel | Elevated | Stabilized | Moderate |
Market volatility affects these prices. Fastmarkets notes that supply chains for lithium and other battery materials often face imbalances. Geopolitical tensions and new mining regions, such as Latin America and Africa, also influence costs. When raw material prices drop, battery pack prices typically follow — though there is a lag of several months due to long-term contracts. This direct link makes raw materials a key variable for forward procurement planning.
Manufacturing Advances
Manufacturing improvements have consistently lowered lithium battery prices. Factories now use advanced automation and more efficient cell formats, allowing higher output at lower unit costs. U.S. Bureau of Economic Analysis data shows that domestic energy storage battery manufacturing output grew by 57.6% between 2020 and 2023.
The shift from lead-acid to lithium-ion accelerated through the 2010s as manufacturers invested in new processes and equipment. Chinese producers lead global production with cost advantages from lower labor costs, energy inputs, and vertically integrated supply chains. BYD, for example, reduced LFP cell prices to approximately $44/kWh through large-scale production and integration from mine to pack.
LFP chemistry adoption has played a central role in sustaining pack price declines. LFP cells use no cobalt or nickel, rely on more abundant materials, and offer longer cycle life than NMC. As adoption expanded in 2025 across EV, stationary storage, and industrial applications, blended manufacturing costs fell even as the raw material environment tightened.
Policy Impact
Government policy shapes both price levels and market structure. The U.S. Infrastructure Investment and Jobs Act and the Inflation Reduction Act provide subsidies for domestic battery production and add tariffs on imported batteries. In 2024, U.S. lithium-ion battery prices were approximately 90% higher than Chinese imports before subsidies and tariffs were applied.
Policy effects work in two directions. Subsidies and mandates accelerate domestic demand and production, supporting scale and competition over time. Tariffs and localization requirements raise short-term costs but reduce supply chain exposure. In China, VAT rebate policy changes on battery exports in 2025 contributed to timing effects in procurement, pulling forward demand and supporting the Q4 price recovery in raw materials.
These dynamics interact with manufacturing trends and raw material prices to produce the price environment buyers face. Tracking policy changes in key markets remains important for forecasting procurement costs.
Application Breakdown
Lithium battery prices and value propositions vary significantly by end use. EV, solar storage, consumer electronics, and material handling each involve different capacity ranges, chemistry preferences, and cost structures.
EVs
EV battery packs rely on lithium-ion cells for driving range and performance. Over the past few years, the lithium battery price for EV applications dropped by 20% to 50% as production shifted to lower-cost manufacturing regions. Specialty batteries produced in the U.S. and Europe for defense or industrial vehicles remain considerably more expensive than mass-produced packs from Asia.
Automakers have increased battery capacity in new EV models, but research shows that vehicle transaction prices have risen more than the underlying reduction in battery costs. Cost savings from declining battery prices have not flowed through proportionally to end consumers. Global EV sales grew 22% in 2025, with particularly strong performance in China, Europe, and emerging markets, according to Benchmark Mineral Intelligence data.
EV battery prices have declined substantially as production concentrates in lower-cost regions, but the savings are not always fully reflected in vehicle retail prices.
Solar Storage
Solar storage systems use lithium-ion batteries to store energy from solar panels for later use. Battery prices for this segment have declined approximately 97% since 1991, and the trend continued through 2025. Between 2014 and 2018 alone, prices halved as production volumes grew and technology matured.
In residential solar home systems, lithium-ion batteries cost more upfront than lead-acid alternatives. A 170 Wh lithium-ion battery costs around $160, compared to approximately $45 for a comparable lead-acid unit. Despite this difference, lithium-ion batteries deliver approximately 25% lower total energy cost over their lifetime because of longer service life and higher cycle efficiency. A 2.5 kWh lithium-ion pack for a solar home system cost approximately $1,190 in 2020, with cells accounting for nearly 60% of that figure.
In 2025, commercial BESS pack prices fell to $70/kWh, marking a significant drop in the cost of energy storage systems and making grid-connected and behind-the-meter commercial storage projects economically viable at a scale that was not achievable two years ago.
Consumer Electronics
Consumer electronics such as smartphones, laptops, and tablets depend on small lithium-ion cells. These devices benefit from the same manufacturing scale and cost reduction trends as larger applications. As production volumes grow and cell designs improve, battery costs for consumer electronics continue to fall, allowing manufacturers to improve performance without raising device prices.
Key outcomes for buyers:
- Lower device prices as battery costs decline
- Longer battery life from higher energy density
- Improved safety and reliability from advanced cell management
Material Handling
Material handling equipment — forklifts, pallet jacks, warehouse robots, and automated guided vehicles (AGVs) — relies heavily on lithium batteries in 2025. These machines operate in factories, warehouses, and distribution centers where uptime and energy efficiency directly affect operating costs.
Lithium batteries are preferred for material handling because they charge faster, last longer, and require no maintenance tasks such as watering or equalization. Workers can operate equipment for more hours per shift, and maintenance labor is reduced substantially compared to lead-acid alternatives.
In 2025, a typical lithium battery for a Class I or II forklift costs between $7,000 and $15,000 depending on capacity and brand. Smaller units for pallet jacks and AGVs range from $2,000 to $6,000.
| Equipment Type | Battery Capacity (kWh) | Price Range (USD) |
|---|---|---|
| Forklift (Class I/II) | 14 to 40 | $7,000 to $15,000 |
| Pallet jack | 2 to 5 | $2,000 to $4,500 |
| AGV / robot | 3 to 10 | $3,000 to $6,000 |
Lithium batteries in material handling typically deliver 2,000 to 4,000 charge cycles, up to five times longer than lead-acid alternatives. Built-in battery management systems (BMS) monitor temperature, voltage, and current in real time, preventing overheating and extending service life. Companies that switch from lead-acid to lithium in forklift fleets typically recover the upfront investment within two to four years through reduced maintenance and replacement costs.
Key benefits:
- Longer lifespan and higher cycle count
- Faster charging with opportunity charging during breaks
- Lower maintenance with no watering or equalization required
- BMS-based protection for safety and longevity
Regional Differences
Lithium battery prices differ by region because of manufacturing scale, labor costs, energy prices, and government policy. Asia maintains the lowest finished pack prices globally. Europe and North America pay a premium due to higher production costs and less mature local supply chains.
Asia
Asia leads the world in lithium battery production and cost competitiveness. China, South Korea, and Japan host the largest manufacturers, with China benefiting from vertically integrated supply chains, lower labor costs, and strong government support. In 2025, Chinese battery packs average $84/kWh, approximately 31% less than comparable packs in the United States.
Price trends in Asia are sensitive to supply, demand, and regulatory changes. Q1 2025 saw price movements driven by EV demand, production adjustments around the Chinese New Year, and ongoing oversupply effects from 2024. The Jianxiawo mine suspension in August 2025 triggered sharp moves in raw material prices across the region.
| Quarter | Asia Pacific Price Trends and Drivers |
|---|---|
| Q1 2025 | Price swings from EV demand, production disruptions, oversupply, and VAT policy changes |
| Q4 2024 | Stabilization and price recovery from EV demand and government stimulus |
| Q3 2024 | Sharp price drop from oversupply, trade tensions, and new cell chemistries |
| Q2 2024 | Price rise from energy storage and EV interest, offset by regulatory and logistics challenges |
| Q1 2024 | Substantial price variation from oversupply and low demand |
Europe
Europe faces higher lithium battery prices than Asia due to stricter regulations, higher labor costs, and less mature local manufacturing. Countries including Germany, France, and the United Kingdom invest heavily in battery production and EV policy, but domestic supply chains remain in development.
In early 2025, European prices increased due to raw material cost pressure and mixed EV demand trends. Falling new vehicle registrations and supply chain issues contributed to price instability through late 2024. The European battery market reached $109.9 billion in 2023 and is projected to grow to $221.7 billion by 2029, driven by EV adoption, energy storage demand, and government electrification support.
The European battery market reached $109.9 billion in 2023 and is projected to grow to $221.7 billion by 2029, driven by EV adoption, energy storage demand, and government electrification support. Spain’s €700 million BESS program alone targets 2.5–3.5 GW of new storage capacity, covering up to 85% of project costs across more than 100 initiatives.
| Quarter | Europe Price Trends and Drivers |
|---|---|
| Q1 2025 | Price increase from raw material costs; mixed EV demand; policy adjustments |
| Q4 2024 | Instability from excess supply and weak EV demand; price drops and spikes |
| Q3 2024 | Major price decreases from oversupply, weak demand, supply chain disruptions |
| Q2 2024 | Price stability from supply management; slight demand softness |
| Q1 2024 | Price declines from low demand and excess supply |
North America
North American lithium battery prices remain higher than Asia but generally lower than Europe. The U.S. market is shaped by EV demand, federal incentives, and ongoing supply chain localization. In 2025, prices fluctuated as incentive policy changes, restocking patterns, and raw material cost shifts moved through the market.
Major producers including Tesla, LG Energy Solution, and Panasonic operate in North America and influence both pricing and technology direction.
| Quarter | North America Price Trends and Drivers |
|---|---|
| Q1 2025 | Fluctuating prices from EV demand changes, incentive uncertainty, and restocking |
| Q4 2024 | Recovery from tighter compliance standards and improving supply-demand balance |
| Q3 2024 | Considerable price drop from oversupply, logistics costs, and reduced government support |
| Q2 2024 | Relative price stability with balanced supply and demand |
| Q1 2024 | Severe price decrease from low demand and excess supply |
LFP vs. NMC Battery Chemistry

LFP (lithium iron phosphate) and NMC (nickel manganese cobalt oxide) are the two dominant chemistries in the lithium battery market in 2025. The choice between them affects cost, safety, cycle life, and energy density.
LFP batteries avoid cobalt and nickel entirely, which lowers cost and reduces supply chain exposure to price volatility in those materials. LFP also offers a structurally stable cathode, translating to longer cycle life and higher thermal safety. In 2024, LFP cell prices in China dropped below $60/kWh, with manufacturers using high-volume vertical integration reaching approximately $44/kWh.
NMC batteries offer higher energy density, up to 240 Wh/kg compared to 180 Wh/kg for LFP. This makes NMC better suited to long-range EVs and premium electronics where weight and volume are constrained. However, NMC relies on cobalt and nickel, whose prices are more volatile and supply chains more geopolitically concentrated.
Research on EV range economics identified a tipping point at approximately 373.5 miles of vehicle range. For applications below this threshold — including most daily driving use cases and all industrial equipment — LFP provides better economic value.
| Feature | LFP Batteries | NMC Batteries |
|---|---|---|
| Energy density | Lower (180 Wh/kg) | Higher (240 Wh/kg) |
| Cost | Lower | Higher |
| Safety | Higher | Moderate |
| Cycle life | Longer | Shorter |
| Supply chain stability | Strong (no cobalt or nickel) | Sensitive to cobalt and nickel prices |
| Best use cases | Daily driving, solar storage, industrial equipment | Long-range EVs, premium electronics |
For buyers managing total cost of ownership, LFP offers more predictable pricing because it avoids the commodity exposure that affects NMC. For industrial applications such as forklifts, floor machines, and AWP equipment, LFP is the standard chemistry choice. For a full breakdown of how these two chemistries compare across performance, cost, and application fit, see our detailed guide: LFP vs NMC Lithium Battery Comparison.
Long-Term Market Outlook
Most forecasts expect lithium battery pack prices to continue declining beyond 2025, though the pace depends on raw material trends and manufacturing investment. RMI projects that lithium-ion battery costs could fall to between $32 and $54/kWh by 2030, with energy density potentially reaching 600 to 800 Wh/kg. Annual battery sales are expected to rise to between 5.5 and 8 terawatt-hours per year.
The energy storage segment is the fastest-growing application, driven by grid-scale renewable integration and data center power infrastructure. BloombergNEF projects nearly a 5x increase in global lithium demand by end of decade.
| Region | 2023 to 2025 Trends | 2025 to 2033 Forecast |
|---|---|---|
| Latin America | Oversupply, weak EV demand, project delays | Market to grow from $5.70B (2024) to $7.83B (2033) at 3.42% CAGR |
| North America | Low demand, production cuts, gradual stabilization | Cautious procurement; moderate price volatility |
| Asia Pacific | Price drops from oversupply, demand recovery in EV and storage | Prices to stabilize as EV and ESS demand grows |
| Middle East and Africa | Industrial growth, resource availability, geopolitical influences | Regional factors to continue shaping price dynamics |
Near-term upside risk in raw material prices could slow pack price declines or eventually reverse them if the Jianxiawo mine restart remains delayed or if broader Jiangxi province compliance reviews affect additional producers.
FAQ
What is the average lithium battery price per kWh in 2025?
The global average pack price reached $108/kWh in 2025, a record low. China averages $84/kWh. The U.S. and Europe remain approximately 31% and 48% higher respectively.
What is the average lithium battery price per kWh in 2025?
Battery-grade lithium carbonate rose more than 90% from its June trough, driven by energy storage demand growth, low inventory in China, and the suspension of CATL’s Jianxiawo mine. This has not yet pushed up finished pack prices, but introduces upside risk in 2026.
What is the price difference between LFP and NMC batteries?
LFP cell prices in China dropped below $60/kWh in 2024, with some producers reaching $44/kWh. NMC cells cost more due to cobalt and nickel content. For industrial and storage applications, LFP offers lower cost and better total cost of ownership.
How much does a lithium forklift battery cost?
A Class I or II forklift battery costs between $7,000 and $15,000 depending on capacity and brand. Pallet jack batteries range from $2,000 to $4,500.
Will lithium battery prices keep falling in 2026?
BloombergNEF forecasts a further 3% decline to approximately $105/kWh. However, ongoing supply disruptions in Jiangxi province could narrow or reverse this trend.